When you're planning your next investment property refinance, understanding DSCR loan seasoning requirements could make or break your cash flow strategy. These ownership duration rules vary dramatically between lenders, ranging from zero seasoning to up to 12 months of required ownership before refinancing becomes possible.
For real estate investors, this flexibility in seasoning requirements opens up unique opportunities to access capital quickly or plan longer-term investment strategies. The absence of universal seasoning standards means you can shop around for lenders whose requirements align with your specific investment timeline and financial goals.
Understanding DSCR Loan Seasoning Variations
Understanding DSCR loan seasoning requirements variations is crucial for developing an effective investment refinancing strategy. Unlike traditional mortgage products that often have standardized seasoning requirements, DSCR loans offer much more flexibility in ownership duration rules.
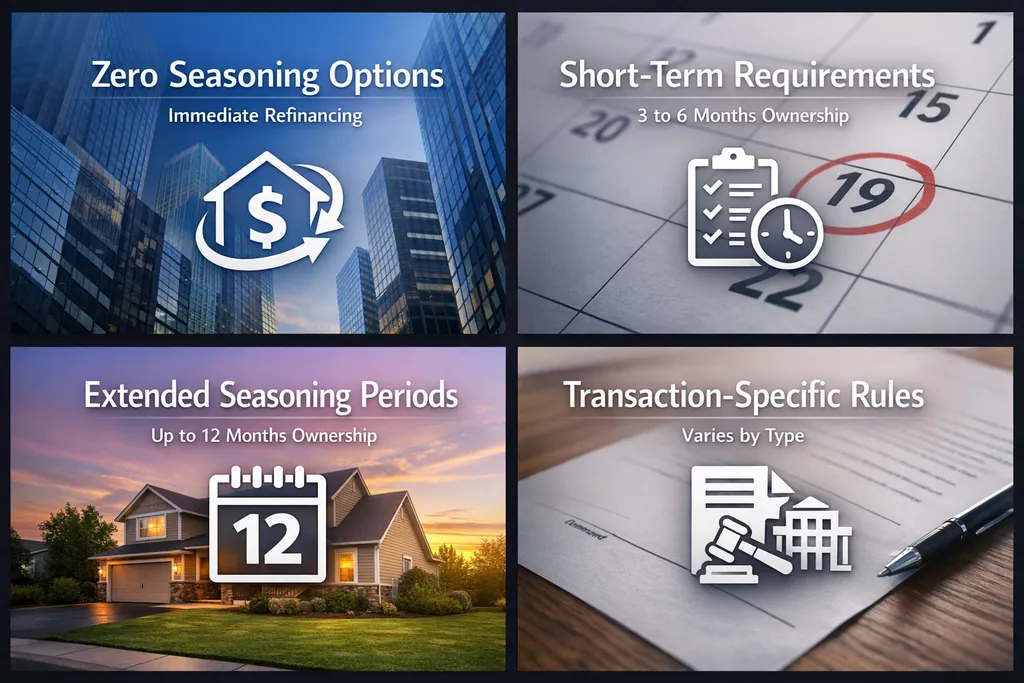
Zero seasoning options: Some lenders allow immediate refinancing post-closing, enabling rapid capital deployment for new investment opportunities
Short-term requirements: Many lenders require between three to six months of ownership before refinance eligibility kicks in
Extended seasoning periods: Conservative lenders might require up to 12 months of ownership, particularly for cash-out refinances
Transaction-specific rules: Seasoning requirements often vary based on the type of refinance, borrower profile, and loan-to-value ratios
Zero Seasoning Benefits for Active Investors
Zero seasoning benefits for active investors can dramatically accelerate portfolio growth and improve cash flow management. When lenders offer no-seasoning DSCR refinances, you're essentially getting immediate access to your property's equity without traditional hold periods.
Rapid capital redeployment: Access cash immediately after closing to fund additional property acquisitions or renovations
Market timing advantages: Capitalize on time-sensitive investment opportunities without waiting for seasoning periods to expire
Enhanced liquidity management: Maintain better cash flow by quickly unlocking equity from recently acquired properties
Competitive market positioning: Especially valuable in fast-paced markets where quick access to capital provides significant advantages
Refinance Eligibility Factors Beyond Seasoning
Refinance eligibility factors beyond seasoning play equally important roles in securing favorable DSCR loan terms. While ownership duration matters, lenders evaluate multiple criteria when determining your refinancing options.
Debt service coverage ratio: Properties must generate sufficient rental income to cover mortgage payments, typically requiring ratios above 1.0
Loan-to-value restrictions: Most lenders cap refinances at 70-80% LTV, regardless of seasoning requirements
Property performance history: Consistent rental income and occupancy rates strengthen your refinancing position
Borrower experience: Your track record as an investor might influence both seasoning requirements and loan terms
Regional Lender Rules and Compliance Considerations
Regional lender rules and compliance considerations add another layer of complexity to DSCR loan seasoning requirements. Different markets often have unique regulations that impact both seasoning periods and refinancing terms.
State-specific regulations: Some states like California have additional requirements that might affect seasoning periods and refinancing options
Local market conditions: Rent control laws and local housing regulations can influence lender seasoning requirements
Lender geographic preferences: Some lenders specialize in specific regions and may offer more favorable seasoning terms in their preferred markets
Portfolio management compliance: Ensure your investment strategy aligns with local regulations while maximizing refinancing opportunities
Strategic Action Steps for DSCR Seasoning Success
Strategic action steps for DSCR seasoning success require careful planning and proactive lender research. Here's your roadmap to navigating seasoning requirements effectively:
Research multiple lenders early: Compare seasoning requirements across different DSCR loan providers before making acquisition decisions
Time your acquisitions strategically: Plan property purchases with your refinancing timeline in mind, especially if you need quick access to equity
Maintain detailed property records: Document rental income, expenses, and property improvements to strengthen your refinancing application
Build relationships with flexible lenders: Establish connections with lenders who offer favorable seasoning terms for your investment strategy
Monitor market conditions continuously: Stay informed about changing lender requirements and market opportunities that might affect your refinancing plans
Cash-Out Refinance Seasoning: Bridge Loans and Cash Purchases
Cash-out refinance seasoning carries its own nuances beyond standard rate-and-term seasoning. Many DSCR programs allow investors to refinance based on current appraised value immediately after closing, which is especially useful for BRRRR (buy, rehab, rent, refinance) strategies and properties acquired with cash.
Cash purchases: Properties bought without existing financing typically face fewer restrictions when refinancing quickly, since there's no prior loan to season against, and clear title can support expedited processing.
Bridge-to-DSCR transitions: Investors who use a bridge loan to acquire and renovate a property often move to permanent DSCR financing once the property is stabilized and generating rental income. A successful transition requires sufficient cash reserves, completed improvements, and established rental income before applying.
Documentation for fast refinancing: Regardless of seasoning flexibility, lenders still expect a current appraisal, rent rolls or lease agreements, and cash reserves generally covering 6-12 months of principal, interest, taxes, and insurance (PITI) per property.
Working with a lender experienced in bridge-to-permanent and cash-out DSCR transactions helps ensure the refinance timing aligns with your investment strategy while reserve and documentation requirements are met. Investors converting a property from commercial to residential use face their own distinct seasoning timeline — see our guide to seasoning after a commercial-to-residential conversion for how that scenario is underwritten.
Mastering DSCR loan seasoning requirements gives you a competitive edge in real estate investing. With seasoning periods ranging from zero to 12 months depending on the lender, you've got the flexibility to match financing options with your investment strategy.
The key is understanding that seasoning requirements aren't one-size-fits-all. Some lenders offer immediate refinancing opportunities that let you quickly redeploy capital, while others require longer ownership periods but might offer better rates or terms.
Take time to research lender-specific requirements and build relationships with those whose seasoning policies align with your investment approach. Whether you're looking for rapid portfolio expansion or long-term wealth building, the right DSCR loan seasoning strategy can significantly impact your success as a real estate investor.