Most real estate investors know that traditional mortgage lenders collect property taxes and insurance in monthly escrow accounts. But here's the thing: DSCR loans often allow you to waive those impounds altogether. A DSCR loan property tax escrow waiver gives you the option to pay taxes and insurance directly instead of bundling them into your monthly payment. For investors managing multiple properties with staggered tax deadlines, that flexibility can be a game changer.
Controlling when and how you pay property obligations means better cash flow management and fewer surprises. Instead of locking up capital in an escrow account every month, you can deploy that money into new deals, handle renovations, or simply keep it liquid for opportunistic buys. Yet not every investor qualifies for an escrow waiver, and some lenders attach fees or tighter underwriting standards when you choose to go this route.
This guide walks through the mechanics of waiving escrow on a DSCR loan, the eligibility criteria that matter most, and the strategic reasons why investors pursue this option. We'll also cover the potential costs and tradeoffs so you can decide whether an escrow waiver aligns with your portfolio goals.
What a DSCR Loan Property Tax Escrow Waiver Actually Means
An escrow account is a reserve fund that the lender manages on your behalf. Each month, a portion of your mortgage payment goes into this account, and the lender uses those funds to pay your property taxes and homeowners insurance when they come due. The arrangement protects the lender by ensuring those critical bills get paid on time, but it also ties up your capital in an account you don't control.
When you secure a DSCR loan property tax escrow waiver, the lender agrees to let you skip those monthly impounds. Instead, you take full responsibility for paying property taxes and insurance directly to the county and your carrier. This arrangement gives you immediate access to cash that would otherwise sit idle in escrow, and it lets you time those large payments around your rental income cycles.
From a lender's perspective, waiving escrow introduces risk. If you miss a tax payment, the county can place a lien on the property, which jeopardizes the lender's collateral. That's why escrow waivers typically come with stricter eligibility requirements, lower loan-to-value thresholds, or additional fees.
For investors, the decision hinges on two factors: whether you qualify under the lender's guidelines and whether the operational benefit outweighs any added cost or complexity. If you already manage several properties and prefer consolidated control over payment timing, an escrow waiver can simplify your workflow and improve liquidity.
DSCR Loan Escrow Waiver Eligibility Criteria
Lenders evaluate several factors when deciding whether to approve an escrow waiver. Lower leverage typically improves your chances because it reduces the lender's exposure. When you borrow a smaller percentage of the property's value, the lender has a bigger equity cushion and feels more comfortable letting you handle taxes and insurance independently.
Loan-to-Value Ratio: Many lenders cap escrow waivers at a certain LTV threshold, often around 75% or 80%. If your loan amount pushes beyond that ceiling, the lender may require escrows regardless of your credit or experience.
Credit Score: A strong credit profile signals financial discipline and reassures the lender that you'll stay current on all obligations. While DSCR loans focus on property cash flow rather than personal income, credit still matters when you're asking the lender to waive a protective layer.
Property Type and Location: Some lenders restrict escrow waivers to single-family rentals or limit them in states with high property tax volatility. If you're financing a multifamily building or a property in a jurisdiction with complex tax structures, the lender may insist on impounds.
Borrower Experience: Although not always a formal requirement, investors with proven track records managing rental portfolios often find it easier to negotiate waivers. Lenders trust seasoned operators to stay on top of tax and insurance deadlines.
Meeting these criteria doesn't guarantee approval, but it positions you as a lower-risk candidate. If you fall short on one dimension, such as LTV, you might still secure a waiver by offering a higher credit score or additional reserves.
Can You Waive Escrow on a DSCR Loan Without Extra Fees
Whether you can skip escrow without paying a premium depends on your lender's policy and your loan profile. Some lenders offer escrow waivers at no added cost when you meet conservative LTV and credit benchmarks. Others charge an upfront fee, a slightly higher interest rate, or both to offset the perceived risk.
Flat Waiver Fee: A one-time charge at closing, typically ranging from a few hundred to over a thousand dollars depending on loan size. This fee compensates the lender for the administrative burden and risk of monitoring your tax and insurance compliance without holding funds in reserve.
Rate Adjustment: Instead of a flat fee, the lender may add a small increment to your interest rate, such as 0.125% or 0.25%. Over the life of a loan, that adjustment can exceed the cost of a one-time fee, so it pays to run the math before you choose.
No Fee at Lower Leverage: If you bring a larger down payment and your LTV sits well below the lender's waiver threshold, you might qualify for an escrow waiver with no additional cost. This scenario is more common when you're refinancing a property with substantial equity.
Ultimately, the cost-benefit analysis depends on how much capital you free up and what you plan to do with it. If you're earning strong returns on another investment or using the liquidity to close a new deal, a modest fee or rate bump might be worth the tradeoff. On the other hand, if the lender's waiver terms push your effective borrowing cost too high, keeping the escrow account in place could be the smarter play.
Why Investors Pursue a DSCR Loan Without Tax and Insurance Escrow
Cash flow control sits at the top of the list. When you manage multiple properties, tax bills arrive at different times of the year depending on the county. If all your mortgages include escrow accounts, you're making 12 equal payments per property regardless of when the actual tax deadline hits. That creates a mismatch between your outlays and your rental income cycles.
By waiving escrow, you align large payments with periods of strong cash flow or simply plan ahead to set aside funds on your own schedule. Some investors prefer to hold that capital in a high-yield savings account or short-term investment until the tax bill is due, capturing a small return instead of letting it sit in a zero-interest escrow account.
Another reason is administrative simplicity. If you already use accounting software to track expenses across a portfolio, adding property tax and insurance payments to your workflow is straightforward. You avoid the frustration of escrow shortages or overages, which can fluctuate year to year and force surprise adjustments to your monthly payment.
For seasoned investors, waiving escrow is also a signal of financial maturity. It demonstrates to lenders and partners that you're capable of managing obligations independently, which can strengthen relationships and open doors to more flexible financing terms on future deals.
That said, skipping escrow isn't for everyone. If you struggle with cash flow discipline or prefer the convenience of bundled payments, keeping the escrow account might reduce stress and ensure you never miss a deadline.
Step-by-Step: How to Request an Escrow Waiver on Your DSCR Loan
Requesting an escrow waiver starts during the application process, but you can also explore it when refinancing an existing DSCR loan. Here's how the process typically unfolds.
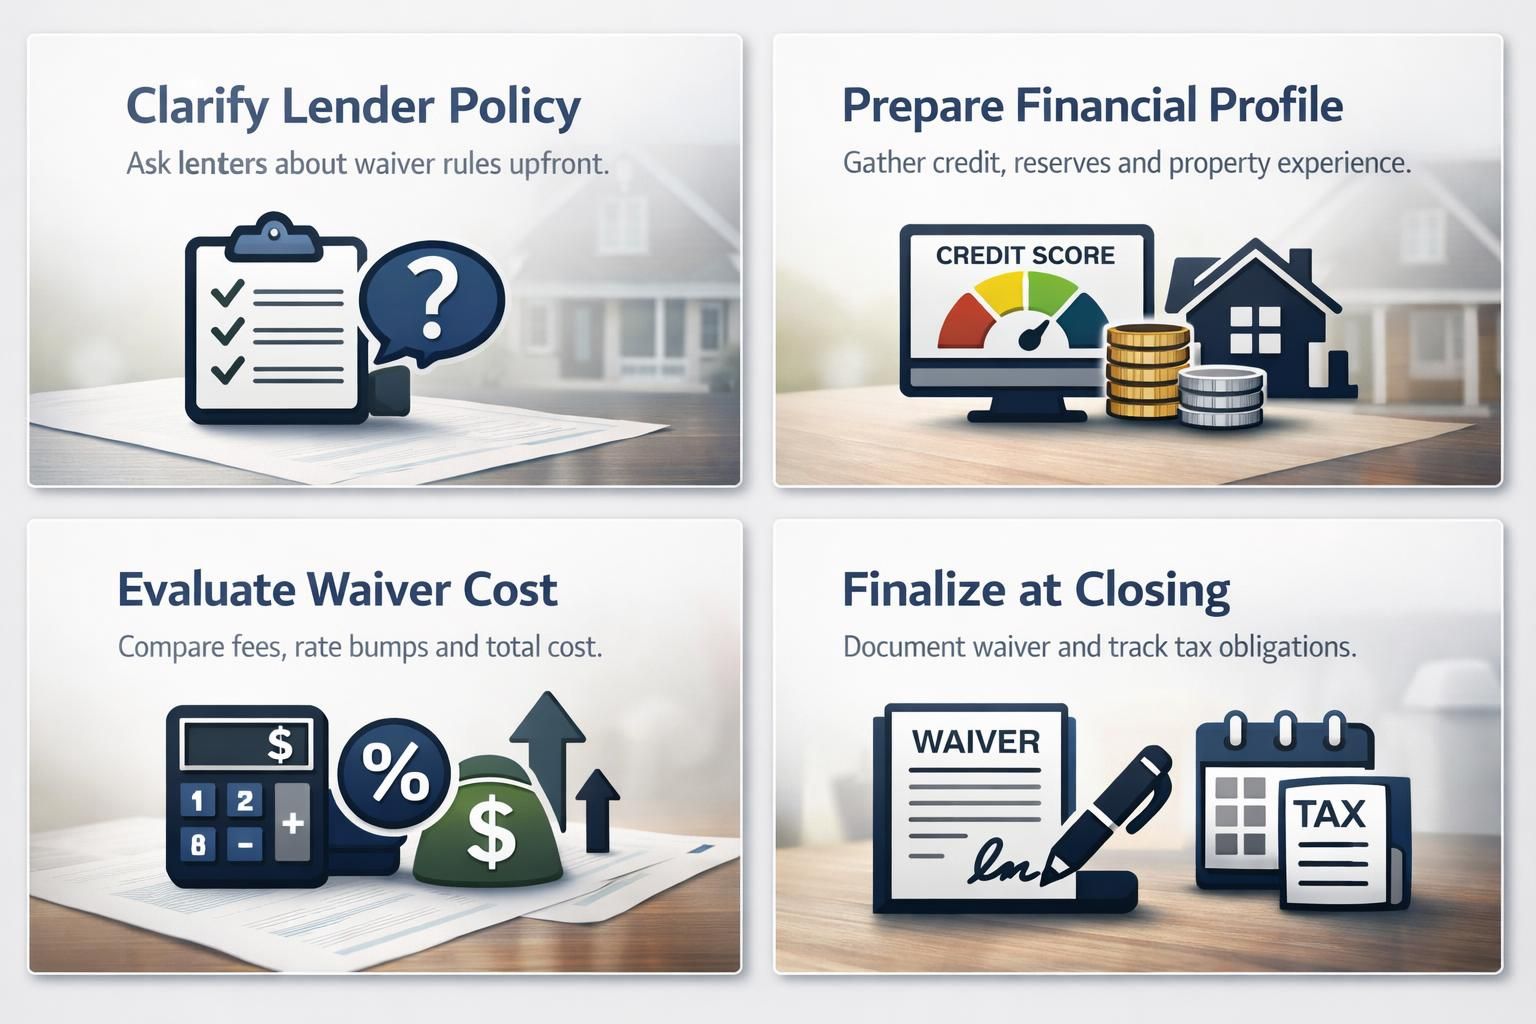
Clarify Lender Policy Early: Before you submit a full application, ask the lender whether they allow escrow waivers on DSCR loans and under what conditions. Some lenders advertise this feature prominently, while others handle it on a case-by-case basis. Knowing the guidelines upfront helps you set realistic expectations and avoid wasted effort.
Prepare Your Financial Profile: Gather documentation that demonstrates strong creditworthiness, adequate reserves, and experience managing rental properties. If you're borderline on LTV, consider whether you can increase your down payment to improve eligibility. Lenders want to see that you have the discipline and resources to handle tax and insurance payments independently.
Evaluate the Cost: Once the lender confirms you're eligible, review any fees or rate adjustments associated with the waiver. Compare the total cost over the loan term against the operational benefits you expect to gain. If the waiver fee is modest and you'll free up several thousand dollars in escrow, the math usually works in your favor.
Finalize at Closing: If you move forward, the escrow waiver will be documented in your loan agreement. Make sure you understand your obligations: you'll need to provide proof of insurance annually and confirm that property taxes are paid on time. Missing a payment can trigger default provisions and jeopardize your financing.
After closing, set up automated reminders or calendar alerts for tax and insurance deadlines. Many investors open a dedicated savings account to hold funds earmarked for these expenses, mimicking the escrow structure but maintaining full control over the timing and use of the money.
Comparing Lender Policies on Escrow Waivers
Not all DSCR lenders treat escrow waivers the same way. Some institutions view waivers as a standard feature for experienced investors, while others reserve them for borrowers who meet stringent criteria or pay a premium. Understanding these differences helps you shop effectively and negotiate better terms.
Large banks and traditional mortgage companies tend to require escrows on most investor loans, especially at higher leverage. Their underwriting systems prioritize risk mitigation, and escrow accounts fit neatly into that framework. If you're borrowing from a conventional lender, expect tighter restrictions and less flexibility around waivers.
Private lenders and portfolio lenders often offer more latitude. Because they hold loans on their own balance sheets rather than selling them to secondary markets, they can tailor terms to match the borrower's profile. If you bring strong financials and a proven track record, these lenders may approve an escrow waiver with minimal friction.
Another variable is whether the lender services the loan in-house or outsources servicing to a third party. In-house servicing sometimes makes escrow waivers easier to administer because the lender maintains direct oversight. When servicing is outsourced, the servicer's policies can introduce additional constraints even if the originating lender is flexible.
Geography also plays a role. In states where property taxes are due annually in a lump sum, lenders might be more comfortable with escrow waivers because the payment schedule is predictable. In jurisdictions with semi-annual or quarterly tax bills, lenders may worry about missed deadlines and insist on impounds.
When comparing lenders, ask specific questions: What's the maximum LTV for an escrow waiver? Is there a fee, and if so, how much? What documentation do you need to provide annually? These details can make the difference between a waiver that saves you money and one that adds unnecessary complexity.
Common Mistakes to Avoid When Waiving Escrow
Waiving escrow gives you control, but it also shifts full responsibility onto your shoulders. Missing a tax payment or letting insurance lapse can trigger serious consequences, including default on your loan and potential foreclosure. Here are pitfalls to watch out for.
First, underestimating the discipline required to set aside funds. Without the automatic monthly deduction, it's tempting to spend the extra cash flow on other priorities. If you don't proactively save for tax and insurance bills, you'll scramble when deadlines arrive. Open a separate account and treat it like an escrow fund, even though you control it.
Second, failing to monitor tax assessments. Property tax bills can increase year over year, especially after renovations or in hot markets. If you budget based on last year's amount and the county raises your assessment, you might come up short. Review your tax notices carefully and adjust your savings accordingly.
Third, neglecting insurance renewals. Lenders typically require proof of continuous coverage, and lapses can violate your loan agreement. Set calendar reminders well before your policy expires, and keep digital copies of declarations pages so you can submit them promptly when the lender requests.
Fourth, choosing an escrow waiver when you're already stretched thin. If you're managing multiple properties or dealing with high vacancy rates, the convenience of bundled payments might outweigh the benefits of controlling your own funds. Be honest about your cash flow situation before you opt out of escrow.
Finally, ignoring lender communications. Some lenders conduct annual audits to verify that taxes and insurance are current. If you miss a request for documentation, the lender may force-place insurance or demand that you reinstate escrows. Stay responsive and keep your records organized.
A DSCR loan property tax escrow waiver offers real estate investors a powerful tool for managing cash flow and optimizing liquidity. By taking control of when and how you pay property taxes and insurance, you can align large outlays with your income cycles, reduce idle capital, and simplify your administrative workflow across a multi-property portfolio.
Eligibility depends on factors like loan-to-value ratio, credit score, and lender policy. Lower leverage typically makes waivers easier to secure, while some lenders charge fees or rate adjustments to offset the added risk. The key is to evaluate whether the operational benefits justify any extra cost and whether you have the discipline to manage payments independently.
For investors who value flexibility and control, waiving escrow can be a smart strategic move. But it's not a one-size-fits-all solution. If you prefer the predictability of bundled payments or worry about missing deadlines, keeping an escrow account in place might be the safer choice.
Before you decide, compare lender policies, run the numbers on fees and rate adjustments, and assess your own financial habits. If you're confident in your ability to stay on top of tax and insurance obligations, an escrow waiver can free up capital and give you greater command over your investment strategy. Ready to explore your options? Get a personalized DSCR loan quote and find out if an escrow waiver fits your portfolio goals.