Maximum DSCR Loan Amounts: What's the Real Ceiling?
August 21, 2026
•
7 min read
Understanding Maximum DSCR Loan Amount Limits for Real Estate Investors
When evaluating what is maximum loan amount for DSCR financing, real estate investors need to understand the various factors that determine loan size limits. DSCR loans offer unique advantages for rental property investments and fix-and-flip projects, but knowing the maximum loan amounts available can significantly impact your investment strategy. These limits vary based on lender policies, property values, and market conditions, making it essential for investors to understand how loan size limits affect their purchasing power and portfolio growth potential.
DSCR Loan Amount Ranges
DSCR loan amount ranges provide investors with flexibility across different investment scales and property types. Understanding these ranges helps investors match their financing needs with appropriate loan products.
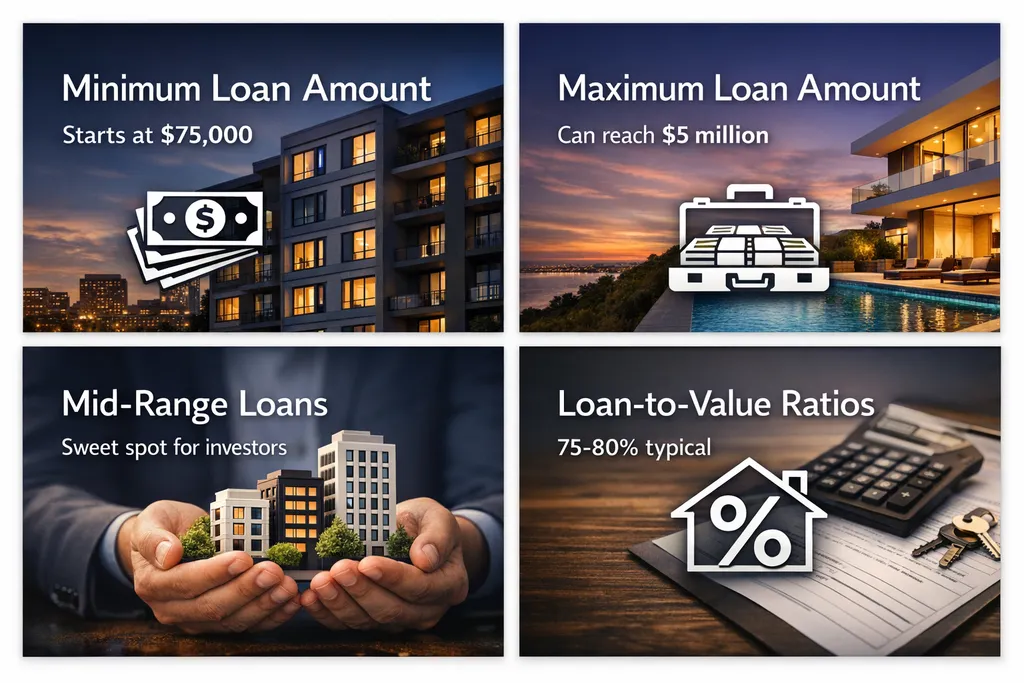
Minimum loan amounts typically start at $75,000, making DSCR loans accessible for smaller investment properties and entry-level rental units
Maximum loan amounts can reach up to $5 million, accommodating large-scale commercial properties and high-value residential investments
Mid-range loans between $200,000 and $1 million often represent the sweet spot for most rental properties investors seeking competitive terms
Loan amounts depend heavily on property value, with most lenders offering up to 75-80% loan-to-value ratios for investment properties
Jumbo Loan Thresholds Impact
Jumbo loan thresholds create important considerations for investors purchasing higher-value properties, as these limits affect both qualification requirements and loan terms.
Properties exceeding $832,750 may require jumbo loan products with different underwriting standards and potentially higher interest rates
Conforming loan limits vary by geographic area, with high-cost regions having different thresholds that impact financing options
Jumbo loans often require larger down payments and stronger financial qualifications compared to conforming loan amounts
Investors should factor jumbo loan requirements into their deal analysis when evaluating properties near or above these thresholds
Lender-Specific Loan Caps
Lender-specific loan caps vary significantly across different financial institutions, creating opportunities for investors to shop for optimal loan size limits that match their investment goals.
Private lenders often offer higher maximum loan amounts compared to traditional banks, sometimes reaching $5 million or more for qualified investors
Portfolio lenders may have more flexible loan size limits since they keep loans on their books rather than selling to secondary markets
Credit unions and community banks might have lower maximum loan amounts but could offer more competitive rates for smaller deals
Non-bank lenders specializing in investment properties typically provide the highest loan caps for DSCR products
DSCR Requirements Affecting Loan Size
DSCR requirements directly impact the maximum loan amount investors can qualify for, as lenders evaluate rental income potential against debt service obligations.
Maintaining a debt service coverage ratio above 1.20 typically qualifies investors for maximum loan amounts available from most lenders
Higher DSCR ratios between 1.25 and 1.30 may unlock better terms and higher loan limits for qualified properties
Properties with strong rental income potential can support larger loan amounts when the DSCR calculation demonstrates adequate cash flow coverage
Investors should calculate potential DSCR ratios before applying to ensure they can qualify for their desired loan amount
Maximizing Your DSCR Loan Potential
Maximizing your DSCR loan potential requires strategic planning and understanding of what is maximum loan amount for DSCR products across different scenarios and lender requirements.
Research multiple lenders to compare maximum loan amounts and find institutions that specialize in your target investment size
Improve property cash flow projections through market rent analysis and expense optimization to support higher loan amounts
Consider portfolio relationships with lenders who may offer higher limits for repeat investors with proven track records
Evaluate the unlimited loan count advantage of DSCR products to scale your investment portfolio without traditional financing strategies restrictions
Plan for jumbo loan requirements when targeting higher-value properties by preparing stronger financial documentation and larger down payments
What Actually Sets Your Maximum Loan Amount
Rather than a single number, your maximum DSCR loan amount comes from the interaction of several factors.
Lender program caps: Each lender sets its own ceiling for DSCR products, and these caps vary and change over time.
DSCR ratio strength: A higher ratio gives the lender more comfort extending a larger loan relative to the property's income.
Loan-to-value requested: Borrowing a lower percentage of the property's value generally supports a larger absolute loan amount within a lender's guidelines.
Property type and appraised value: The appraisal ultimately caps how much can be borrowed against a given property, regardless of your qualification strength.
DSCR Loan Amount FAQs
Is there a hard cap on DSCR loan amounts?
Not a single universal cap. Individual lenders set their own maximum loan amounts, which can range from around $1 million to $5 million or more for well-qualified borrowers, though these figures shift over time and by lender.
Does DSCR loan amount affect my interest rate?
It can. Some lenders apply pricing tiers based on loan size, and jumbo-range DSCR loans may carry different pricing or additional requirements compared to smaller, more standard loan amounts.
Can I combine multiple properties into one large DSCR loan?
Some lenders offer blanket loans that finance several properties under a single loan, which can be a way to reach higher combined loan amounts. This is a different product structure than a standard single-property DSCR loan.
What increases my maximum loan amount?
A stronger DSCR ratio, a lower loan-to-value request, a higher credit score, and larger cash reserves generally all work in your favor when a lender is determining how much they're willing to lend.
Understanding what is maximum loan amount for DSCR financing empowers real estate investors to make informed decisions about their investment strategies. With loan amounts ranging from $75,000 to $5 million and the flexibility to secure unlimited loans based on individual property performance, DSCR products offer significant advantages for portfolio growth. Success depends on understanding jumbo thresholds, maintaining strong DSCR ratios, and working with lenders who specialize in investment property financing. By leveraging these insights, investors can optimize their financing approach and scale their real estate portfolios effectively.