DSCR Loan With Bad Credit: Qualify With a 600+ FICO Score (2026)
August 20, 2026
•
7 min read
Real estate investors often face unique financing challenges, especially when credit scores don't reflect their actual investment expertise or property performance. Getting a DSCR loan with bad credit might seem like an uphill battle, but it's far from impossible. Unlike traditional mortgages that heavily weigh personal credit history, DSCR loans focus primarily on the property's ability to generate income and cover its debt obligations.
For investors who've experienced credit setbacks, business transitions, or simply carry higher utilization due to portfolio growth, understanding how lenders approach risk pricing can open doors. While a pristine credit score certainly helps, the DSCR loan structure offers more flexibility than conventional financing products. That said, lower credit scores typically come with adjustments to terms, rates, and down payment requirements.
This guide walks through practical strategies for securing DSCR financing when your credit isn't perfect. We'll explore how lenders evaluate applications, what minimum thresholds you might encounter, and actionable steps to improve your approval odds and loan terms.
How to Prepare Your Application for DSCR Approval
How to prepare your application for DSCR approval starts with understanding what documentation lenders prioritize when credit scores fall below their preferred ranges. While your personal creditworthiness matters, DSCR lenders place significant emphasis on the investment property's financial performance and your ability to structure a strong application package.
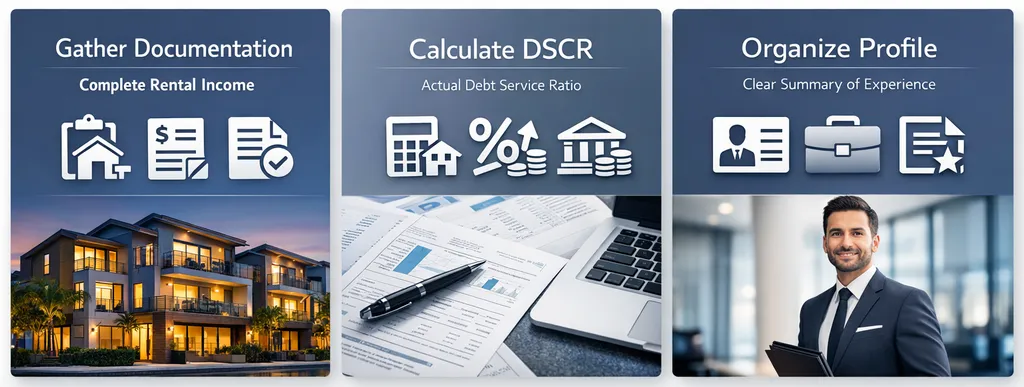
Gather complete rental income documentation: Compile current lease agreements, rent rolls for multi-unit properties, and ideally 12 to 24 months of deposit history showing consistent cash flow. If the property is vacant or newly acquired, obtain a professional rent appraisal or market analysis demonstrating realistic rental income potential. Lenders calculate DSCR by dividing the property's monthly rental income by its monthly debt obligations, so accurate income documentation is critical.
Calculate your actual debt service coverage ratio: Before applying, run your own numbers. Add up the proposed monthly mortgage payment including principal, interest, taxes, insurance, and any HOA fees. Divide your documented monthly rental income by this total. Most DSCR lenders look for ratios above 1.0, with many preferring 1.25 or higher. When your credit is challenged, a stronger DSCR can offset risk concerns and improve your approval odds.
Organize your property and financial profile: Create a clear summary of your real estate investment experience, current portfolio holdings, and exit strategies. Include property tax records, insurance quotes, and repair estimates if applicable. Demonstrate that you understand the market and have contingency plans. Even with limited credit history in the traditional sense, showing investment competence can influence underwriting decisions positively.
Understanding Minimum Credit Score Requirements and Low FICO Options
Understanding minimum credit score requirements and low FICO options helps set realistic expectations when getting a DSCR loan with bad credit. Different lenders maintain varying thresholds, and the floor for approval can shift based on other compensating factors in your application.
Research lender-specific credit minimums: DSCR loan programs typically accept credit scores that would disqualify borrowers from conventional financing. Some lenders may work with investors whose scores fall into the 600 to 640 range, while others set minimums at 660 or higher. A small number of specialized portfolio lenders might consider scores below 600 if the property fundamentals and down payment are exceptionally strong, though this is less common and comes with significant rate adjustments.
Evaluate how credit tiers affect pricing: Lenders use risk-based pricing models that adjust interest rates and fees according to credit bands. An investor with a 680 score might receive a rate 0.5 to 1.5 percentage points higher than someone with a 740 score, all else being equal. Understanding these pricing tiers helps you calculate whether the higher cost of capital still makes your investment deal profitable. Request rate quotes across your actual score range rather than idealized scenarios.
Identify compensating factors that expand eligibility: When your credit score sits near the bottom of a lender's range, strengthening other application elements can tip the scales. Larger down payments, typically 25% to 30% or more, demonstrate commitment and reduce lender exposure. A higher DSCR, strong cash reserves covering six to twelve months of payments, and a track record of successful rental property management can all help compensate for lower credit scores and potentially improve your rate tier.
Strategies to Strengthen Your Loan Terms Despite Credit Challenges
Strategies to strengthen your loan terms despite credit challenges focus on leveraging the aspects of your financial profile that are within your control. While you can't instantly repair your credit score, you can improve other elements that lenders weigh during underwriting.
Increase your down payment beyond minimums: A larger equity stake reduces the lender's risk and often unlocks better rates and terms. If standard DSCR loans require 20% to 25% down, consider putting 30% to 35% down when your credit is below optimal levels. This approach not only improves approval likelihood but may also help you avoid or reduce additional pricing adjustments tied to your credit tier. Calculate whether the extra capital deployment still leaves you with adequate reserves and acceptable cash-on-cash returns.
Target properties with strong, verified income: Select investment properties with established rental histories, long-term tenants, and income that significantly exceeds the debt service. A property generating a 1.4 or 1.5 DSCR presents much less risk than one barely breaking 1.0, making lenders more willing to overlook credit blemishes. Avoid properties requiring extensive rehabilitation or lease-up periods until your credit profile improves, as these add uncertainty that compounds credit risk concerns.
Build relationships with portfolio lenders and specialty programs: Not all DSCR loan products come from the same underwriting playbook. Portfolio lenders who hold loans on their own books rather than selling them may exercise more flexibility and consider your complete investor story beyond automated credit scoring. Similarly, some loan programs specifically cater to investors with non-traditional credit profiles. Taking time to find the right lender match can result in significantly better terms than applying broadly to programs designed for prime borrowers.
What Risk Pricing Means for Investors With Lower Credit Scores
What risk pricing means for investors with lower credit scores is that the cost of borrowing adjusts to reflect the lender's assessment of default probability. This pricing structure is standard across mortgage lending but particularly transparent in DSCR loan programs, where underwriting focuses more on measurable property metrics than subjective borrower characteristics.
Interest rate adjustments: Your base interest rate typically increases as your credit score decreases. A lender might offer a 7.5% rate to an investor with a 750 score, while the same loan program prices at 8.5% or 9.0% for a borrower with a 640 score. These adjustments vary by lender and market conditions but generally follow predictable patterns across credit tiers. The rate difference translates directly to your monthly payment and overall deal profitability, so running detailed cash flow projections at your actual expected rate is essential.
Loan-level price adjustments and fees: Beyond the base rate, lenders may apply loan-level price adjustments in the form of points or fees. These one-time charges, often expressed as a percentage of the loan amount, compensate for increased risk at closing rather than through ongoing interest. An investor with challenged credit might face an additional 1 to 2 points in fees compared to a prime borrower. While this increases upfront costs, it may result in a slightly lower ongoing rate than rolling all risk pricing into the interest rate alone.
Impact on loan-to-value ratios and reserves: Risk pricing isn't limited to rates and fees. Lenders might also reduce the maximum loan-to-value ratio available to borrowers with lower credit scores, effectively requiring larger down payments. Similarly, reserve requirements covering several months of property expenses might increase from three months to six or nine months for investors with credit challenges. These requirements affect your capital deployment strategy and the number of properties you can acquire simultaneously.
Navigating Lender Flexibility and Program Variations
Navigating lender flexibility and program variations is key when getting a DSCR loan with bad credit, as not all financing sources operate under identical guidelines. The DSCR lending landscape includes national lenders, regional portfolio banks, credit unions, and private capital sources, each with distinct underwriting philosophies and flexibility thresholds.
Portfolio lenders versus aggregators: Some institutions originate DSCR loans and hold them in their own investment portfolios, giving them greater discretion to evaluate applications holistically. These portfolio lenders might consider factors like your local market expertise, property management experience, or business plan in ways that automated underwriting systems cannot. By contrast, lenders who bundle and sell loans must adhere to stricter guidelines that leave less room for exceptions. Understanding which model a lender uses helps you target your applications more effectively.
Geographic and property type preferences: Lender flexibility often varies based on property location and type. Some lenders maintain more conservative credit requirements for properties in markets they consider volatile or unfamiliar, while offering better terms in their core geographic areas. Similarly, single-family rentals in stable neighborhoods might receive more favorable treatment than multi-unit properties or those requiring renovation. Matching your property profile to lenders who actively invest in similar assets can improve both approval odds and terms.
Relationship-based underwriting opportunities: Investors who bring multiple properties or demonstrate plans for ongoing business might find certain lenders willing to extend more flexibility on credit standards. A lender evaluating you for one property might maintain strict credit minimums, but that same institution could relax requirements slightly if you're bringing three properties and establishing a long-term financing relationship. This dynamic is more common with regional banks and credit unions than with large national platforms, but it's worth exploring if you have a substantial pipeline.
What Credit Score Ranges Typically Mean for DSCR Approval
What credit score ranges typically mean for DSCR approval depends on the lender, but most DSCR programs are structured in tiers rather than a single hard cutoff.
Strong tier, roughly 700 and above: Investors in this range typically see the most competitive pricing and the widest range of loan-to-value options.
Moderate tier, roughly 660 to 699: Approval is common, though pricing may be slightly higher and some lenders may ask for a larger down payment.
Below-average tier, roughly 620 to 659: Many DSCR programs still approve loans in this range, particularly when the property's debt service coverage ratio is strong and the investor has cash reserves.
Below 620: Options narrow considerably, but some specialized DSCR lenders will still consider these files with a larger down payment, higher reserves, or a stronger DSCR ratio to offset the credit profile.
These ranges are general industry patterns rather than fixed rules, and actual guidelines vary by lender. The common thread across tiers is that DSCR programs are built to weigh compensating factors, so a lower score does not automatically rule out approval the way it often would with a conventional mortgage.
Compensating factors that tend to carry the most weight include a debt service coverage ratio comfortably above 1.0, six or more months of cash reserves, and a larger down payment than the program minimum. Strengthening even one of these factors can sometimes offset a lower credit score enough to keep a deal moving forward.
Frequently Asked Questions: DSCR Loans With Bad Credit
What is the lowest credit score that can qualify for a DSCR loan?
Most DSCR lenders set a program floor between 620 and 680, though some portfolio lenders will consider scores in the 600 to 619 range when the property's DSCR is strong and the down payment exceeds the standard 20% to 25% minimum.
Will bad credit disqualify me even with a strong DSCR?
Not necessarily. DSCR loans weigh the property's cash flow alongside credit, so a ratio at or above 1.25 can help offset a lower score, though pricing will still reflect the added risk.
How much more will I pay in interest with a lower credit score?
Rate adjustments for credit vary by lender, but in the current 6.25% to 8.00% DSCR rate environment, borrowers with challenged credit typically land toward the higher end of that range rather than below it.
Do I need a bigger down payment with bad credit?
Often yes. While standard DSCR down payments run 20% to 25%, lenders may ask for 25% to 30% or more from borrowers with below-average credit to offset risk.
How many months of reserves should I have on hand?
Standard DSCR reserve requirements typically run 2 to 6 months of PITIA. Borrowers with lower credit scores should budget toward the higher end of that range, since lenders often ask for more cushion to approve the file.
Getting a DSCR loan with bad credit requires more preparation and strategy than financing with pristine credit, but it remains an accessible path for real estate investors focused on property performance. By emphasizing strong debt service coverage ratios, substantial down payments, and verified rental income, you can offset credit concerns that might derail conventional mortgage applications.
The key is understanding that DSCR lenders evaluate risk differently than traditional mortgage underwriters. Your credit score influences pricing and terms, but it doesn't solely determine approval. Investors who take time to strengthen their applications, target appropriate lenders, and select properties with solid income fundamentals can secure financing even when their credit history isn't perfect.
As you move forward, focus on what you can control: property selection, documentation quality, and lender relationships. While working to improve your credit score over time certainly benefits future financing efforts, it shouldn't prevent you from pursuing profitable investment opportunities today. The flexibility built into DSCR loan programs exists precisely to serve investors whose financial profiles don't fit traditional molds but whose properties demonstrate clear income-generating potential.