Can First-Time Investors Get a DSCR Loan With No Landlord Experience?
August 21, 2026
•
7 min read
Getting Started with DSCR Loans for New Real Estate Investors
Many aspiring real estate investors assume they need years of landlord experience to qualify for investment property financing. However, a DSCR loan with no prior landlord experience offers a viable path for newcomers to enter the rental property market. These specialized loans focus primarily on the income-generating potential of the investment property rather than your personal rental management history.
First time investor approval through DSCR loans has become increasingly accessible as lenders recognize that property performance often matters more than borrower experience. Understanding the specific requirements and preparing accordingly can help new investors secure financing for their first rental properties while building a foundation for future real estate investments.
Step 1: Meet the Credit Score Requirements
Meeting the credit score requirements represents the first critical step for securing a DSCR loan with no prior landlord experience. Lenders typically set higher standards for first-time investors to offset the perceived risk factors associated with inexperience.
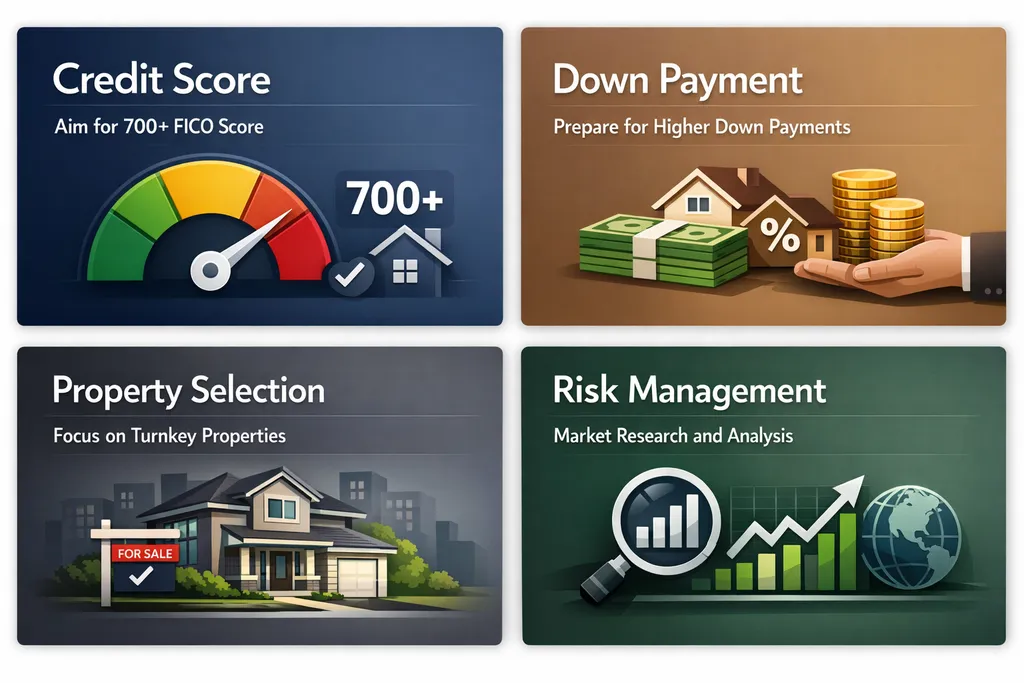
Aim for a 700+ FICO score: First-time investors should target a minimum credit score of 700, which is higher than the 640 score that experienced investors might qualify with from some lenders.
Review your credit report: Check for errors, pay down existing debts, and avoid opening new credit accounts in the months leading up to your loan application.
Build credit history strategically: If your score needs improvement, focus on consistent payment history and maintaining low credit utilization ratios across all accounts.
Consider alternative credit factors: Some lenders may evaluate additional factors like rental payment history or business credit when assessing first-time investors.
Step 2: Secure Adequate Down Payment and Reserves
Securing adequate down payment and reserves becomes crucial when pursuing a DSCR loan with no prior landlord experience. Lenders often require larger cash investments from new investors to mitigate potential risks.
Prepare for higher down payments: Expect to put down 20-25% for your first investment property, with some lenders requiring up to 30% for inexperienced investors.
Maintain cash reserves: Keep 2-6 months of property expenses in reserve accounts, including mortgage payments, insurance, taxes, and estimated maintenance costs.
Document fund sources: Ensure all funds are properly seasoned in your accounts and can be verified through bank statements and other financial documentation.
Consider gift funds carefully: Some lenders may accept gift funds for down payments, but restrictions and documentation requirements vary significantly.
Step 3: Choose Lease-Ready Investment Properties
Choosing lease-ready investment properties ensures compliance with DSCR loan requirements and positions new investors for immediate rental income generation. Property selection becomes particularly important for first time investor approval.
Focus on turnkey properties: Select properties that are move-in ready and can be leased immediately after closing to meet lender requirements for income generation.
Avoid major renovation needs: DSCR loans differ from fix-and-flip financing and typically require properties that don't need substantial repairs or improvements.
Research rental market rates: Ensure the property can generate sufficient rental income to meet debt service coverage requirements in your local market.
Consider property management: Evaluate whether you'll self-manage or hire professional property management, as this affects your net rental income calculations.
Understanding DSCR Loan Benefits for New Investors
Understanding DSCR loan benefits for new investors reveals why these financing options have become popular among those seeking their first rental properties. The unique structure offers several advantages that may offset the lack of landlord experience.
Income-based qualification: Lenders focus on the property's rental income potential rather than your personal employment history or previous landlord experience
Portfolio building potential: These loans can help establish your real estate investment track record, making future property acquisitions easier to finance
Streamlined approval process: Many lenders offer faster processing times compared to traditional investment property loans that require extensive experience documentation
Flexible debt-to-income ratios: Personal debt-to-income ratios may be less restrictive since the property income potential is the primary consideration for approval
Managing Risk Factors as a First-Time Investor
Managing risk factors as a first-time investor helps address lender concerns about approving a DSCR loan with no prior landlord experience. Proactive risk management can strengthen your application and improve approval odds.
Market research and analysis: Conduct thorough research on local rental markets, vacancy rates, and property appreciation trends to demonstrate informed decision-making
Professional property inspection: Invest in comprehensive property inspections to identify potential issues that could affect rental income or require costly repairs
Insurance coverage planning: Secure appropriate landlord insurance policies and understand coverage requirements that lenders may mandate for investment properties
Legal compliance preparation: Familiarize yourself with local landlord-tenant laws, fair housing regulations, and rental property requirements in your investment area
Documentation Checklist for First-Time DSCR Borrowers
Preparing the right paperwork upfront can speed up your approval as a first-time investor. Most DSCR lenders will ask for the following before issuing a final approval.
Government-issued photo ID: Confirms your identity and matches the name on your loan application.
Two to three months of bank statements: Verifies that your down payment and reserve funds are seasoned in your accounts, not borrowed or recently transferred in.
Purchase contract: The signed agreement for the property you intend to finance.
Lease agreement or market rent analysis: Establishes the rental income used to calculate your DSCR ratio.
Entity documents, if applicable: Articles of organization and an EIN letter if you plan to close in an LLC.
Insurance quote: A landlord insurance quote naming the lender as loss payee.
Credit authorization: Permission for the lender to pull your credit report as part of underwriting.
Gathering these documents before you submit your application can shorten the underwriting timeline and reduce back-and-forth requests once your file is in process.
First-Time DSCR Borrower FAQs
Do I need landlord experience to qualify for a DSCR loan?
No. Most DSCR lenders do not require prior landlord experience. Qualification is based primarily on the property's projected or actual rental income rather than your management history.
Will my down payment be higher because I am a first-time investor?
It can be. Down payments on DSCR loans generally run 20% to 25%, and some lenders ask first-time investors for a payment at the higher end of that range or request additional reserves to offset the added risk.
What credit score do I need as a first-time DSCR borrower?
Most DSCR programs set a minimum credit score in the 620 to 680 range. Requirements vary by lender, and a stronger score generally supports better pricing regardless of your experience level.
Can I close my first DSCR loan through an LLC?
Many lenders allow first-time investors to hold title through a newly formed LLC, though some may request a personal guarantee or review your entity's formation documents before approving the loan.
Securing a DSCR loan with no prior landlord experience is achievable for motivated real estate investors who understand the requirements and prepare accordingly. Success typically depends on meeting higher credit standards, securing adequate capital, and selecting income-producing properties that satisfy lender criteria.
The key lies in demonstrating financial stability and choosing properties with strong rental income potential rather than relying on personal experience. First time investor approval through DSCR loans opens doors to real estate investing that might otherwise remain closed to newcomers.
While lender flexibility varies, the fundamental approach remains consistent: focus on property performance, maintain strong personal finances, and work with experienced lenders who understand investment property financing. With proper preparation and realistic expectations, new investors can successfully navigate the DSCR loan process and begin building their rental property portfolios.