Real estate investors who complete renovations often find themselves sitting on untapped equity without a clear plan to leverage it. The best strategies for refinancing after renovation can transform that dormant value into working capital for your next deal. Whether you've just wrapped a fix and flip conversion into a rental or completed strategic upgrades to boost rent, understanding when and how to refinance is critical to portfolio growth.
Refinancing after renovation isn't just about getting a lower rate. It's about capturing the post rehab value you've created, capitalizing on rent increases, and executing smart equity extraction that fuels your investment strategy. For investors working with DSCR loans or rental property financing, the timing and approach you choose can make or break your cash-on-cash return.
This guide walks through actionable refinancing strategies designed specifically for real estate investors looking to maximize returns and scale efficiently. We'll cover timing considerations, valuation tactics, loan product selection, and practical steps to ensure your refinance supports your long-term investment goals.
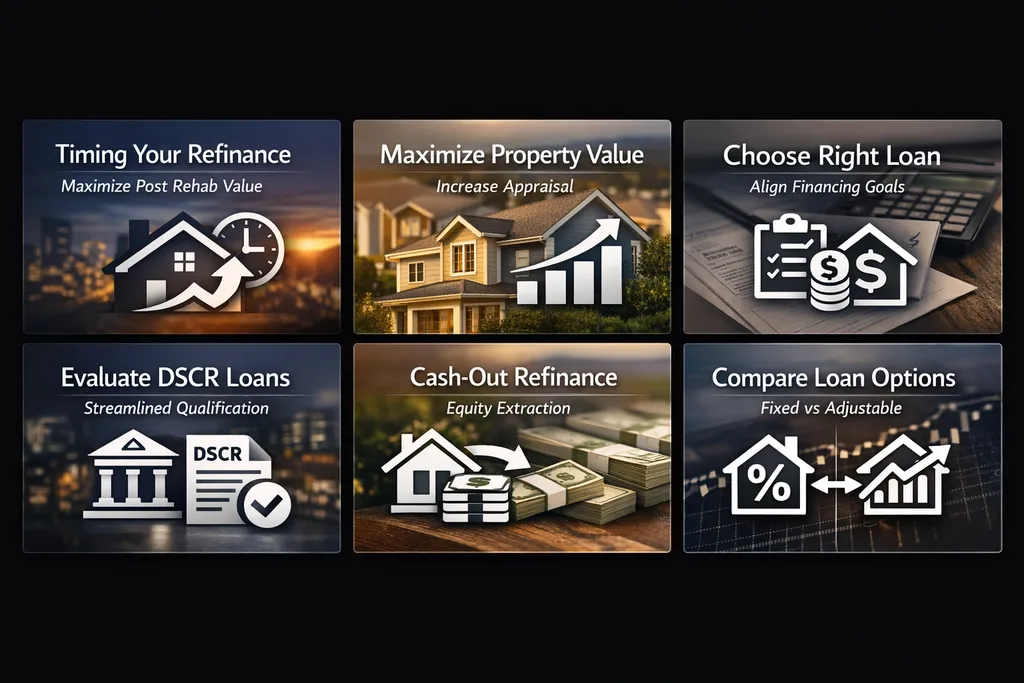
Timing Your Refinance for Maximum Post Rehab Value
Timing your refinance for maximum post rehab value requires careful planning around both property performance and market conditions. Refinancing too early might leave equity on the table, while waiting too long could mean missing favorable rate environments or delaying your next acquisition.
Wait for stabilized rental income: Most lenders require at least three to six months of consistent rental income before they'll refinance based on the new property value. This seasoning period helps demonstrate that your rent increases are sustainable and that the property performs as expected. DSCR loan lenders specifically look at the debt service coverage ratio, which relies on stable rental income to qualify. Rushing the refinance before income stabilizes might result in less favorable terms or a lower appraisal-based loan amount.
Schedule the appraisal strategically: The appraisal drives everything in a refinance transaction, especially when you're trying to capture post rehab value. Consider scheduling your appraisal after you've secured lease renewals or new tenants at higher rates, and after all cosmetic work is complete. Small details like fresh landscaping, clean interiors, and completed punch-list items can influence appraiser perception. If comparable properties in your area recently sold at strong prices, that's often an ideal window to lock in your refinance appraisal.
Monitor interest rate cycles: While you can't time the market perfectly, keeping an eye on rate trends helps you act when conditions align. If rates are rising and you've completed your renovation, it may make sense to refinance sooner rather than later, even if you're only a few months into stabilization. Conversely, if rates are falling and your rental income is already strong, waiting a bit longer might secure better terms. The key is balancing rate environment with your capital needs and portfolio strategy.
How to Maximize Your Property's Increased Value
Maximizing your property's increased value during a refinance starts well before you contact a lender. Documentation and presentation matter significantly when you're asking an appraiser and underwriter to recognize the transformation you've created.
Compile detailed before-and-after records: Gather photos, contractor invoices, permits, and receipts that show the scope and quality of your renovation work. This documentation helps appraisers understand the improvements and may support a higher valuation, especially if your upgrades go beyond cosmetic fixes. Detailed records also streamline the underwriting process, demonstrating that the work was done professionally and that the post rehab value reflects real investment, not just market appreciation.
Provide comparable sales data: Don't rely solely on the appraiser to find the best comps. Research recent sales of similar renovated properties in your area and share that data with your lender and appraiser. If you can show that updated properties are commanding premium prices, it strengthens your case for a higher appraisal. This proactive approach can be particularly helpful in transitional neighborhoods where renovated and unrenovated properties sell at very different price points.
Highlight rent increases and tenant quality: Lenders refinancing rental properties care deeply about income stability. Provide lease agreements showing your post-renovation rent increases, along with tenant screening reports or payment history if available. Demonstrating that you've not only raised rents but also attracted quality tenants reduces perceived risk and may improve your loan terms. Strong rental performance directly supports higher property valuations in income-focused appraisals common with DSCR and investment property loans.
Best Strategies for Refinancing After Renovation: Choosing the Right Loan
Choosing the right loan product is one of the best strategies for refinancing after renovation because it aligns your financing with your investment goals. Not all refinance loans are created equal, and the product you select should reflect whether you're focused on cash flow, equity extraction, or portfolio expansion.
Evaluate DSCR loans for streamlined qualification: DSCR loans qualify you based on the property's rental income rather than your personal income, which makes them particularly attractive for investors with multiple properties or complex tax returns. After renovation, if your property generates strong rent relative to the mortgage payment, a DSCR loan can offer competitive rates and simplified underwriting. This option works well when your primary goal is to refinance quickly and move capital into your next deal without extensive documentation.
Consider cash-out refinance for equity extraction: If your renovation significantly increased the property's value, a cash-out refinance allows you to pull equity out while keeping the property in your portfolio. This strategy is ideal when you want to fund another acquisition, cover holding costs, or reinvest in additional renovations. Keep in mind that increasing your loan balance will affect cash flow, so model your debt service carefully against projected rental income to ensure the property still performs well after the refinance.
Compare fixed-rate versus adjustable-rate options: Your hold strategy should drive your rate choice. If you plan to keep the property long-term as a cash-flowing rental, a fixed-rate refinance offers payment stability and protection against rate increases. If you're planning to sell or refinance again in a few years, an adjustable-rate mortgage might offer lower initial rates, improving short-term cash flow and returns. Weigh the trade-offs based on your portfolio timeline and risk tolerance.
Leveraging Equity Extraction to Scale Your Portfolio
Leveraging equity extraction to scale your portfolio turns your successful renovation into fuel for growth. Many investors view refinancing purely as a way to lower payments, but strategic equity extraction can accelerate acquisitions and increase your overall return on investment.
Reinvest extracted equity into down payments: Pulling equity from a renovated property gives you capital to deploy on your next acquisition without needing to save for months or liquidate other assets. This approach allows you to compound returns by putting your gains to work immediately. Just ensure that the property you're refinancing can still cover its debt service comfortably after the cash-out, so you're not sacrificing cash flow for growth.
Use equity to fund additional renovations: If you have other properties in your portfolio that need upgrades, extracted equity can finance those projects without bringing in outside partners or high-interest debt. This strategy is especially powerful when you can increase rents across multiple properties simultaneously, boosting your overall portfolio performance and preparing additional units for future refinances.
Build liquidity reserves for operating expenses: Real estate investors often tie up too much capital in properties and find themselves cash-poor during vacancy or repair cycles. Using equity extraction to build a reserve fund provides a cushion for unexpected expenses, vacancies, or market downturns. This liquidity can be the difference between weathering a rough patch and being forced to sell at an inopportune time.
Consider tax implications of equity extraction: Unlike sale proceeds, money from a cash-out refinance is typically not taxable because it's borrowed funds, not income. This makes equity extraction a tax-efficient way to access your gains without triggering capital gains taxes. Consult with a tax professional to understand how refinancing fits into your broader tax strategy, especially if you're managing multiple properties or planning future sales.
Common Refinancing Mistakes Investors Make After Renovation
Common refinancing mistakes investors make after renovation can erode returns and create unnecessary stress. Avoiding these pitfalls helps you capture maximum value and keep your portfolio performing efficiently.
Refinancing before rental income stabilizes: Jumping into a refinance immediately after renovations without allowing time for rental income to stabilize often results in lower appraisals or difficulty qualifying. Lenders want to see consistent payment history and occupancy, especially for DSCR loans that rely on property income. Patience during the initial lease-up period usually pays off with better loan terms and higher valuations.
Overlooking closing costs and fees: Refinancing isn't free, and costs can add up quickly between appraisal fees, title work, lender fees, and recording costs. Some investors get so focused on pulling equity or lowering their rate that they don't model whether the refinance actually improves their return once all costs are included. Always calculate your break-even point and ensure the refinance makes financial sense over your hold period.
Ignoring prepayment penalties on existing loans: If your current loan has a prepayment penalty, refinancing early could trigger significant fees that offset any benefit. Review your existing loan documents carefully and factor those costs into your refinance analysis. In some cases, waiting a few more months to avoid a penalty can be the smarter move.
Failing to shop multiple lenders: Not all lenders offer the same rates, terms, or loan products, especially in the investor space. Getting quotes from multiple lenders gives you leverage to negotiate and ensures you're not leaving money on the table. Different lenders may also appraise your post rehab value differently, so casting a wider net can reveal better financing opportunities.
Weighing the Full Range of Alternatives to Cash-Out Refinancing
A cash-out refinance isn't the only way to tap the equity created by a renovation. Depending on your rate environment, portfolio size, and how you plan to deploy the capital, several other structures are worth comparing before committing to a full refinance.
Home equity line of credit (HELOC): A HELOC functions more like a credit line than a lump-sum loan, letting you draw funds as opportunities arise rather than taking the full amount upfront. Because it sits behind your existing mortgage rather than replacing it, it can be a useful option when your current rate is already favorable and a full refinance would mean giving that up. It tends to suit investors funding several smaller projects or acquisitions over time rather than one large deployment.
Fixed-rate home equity loan (second lien): Unlike a HELOC's variable draw structure, a fixed-rate second lien delivers a lump sum with a predictable payment, while still leaving your first mortgage untouched. The tradeoff is that the property now carries two payments instead of one, so it's worth modeling how the added debt service affects your DSCR before moving forward.
Cross-collateralized or blanket loan: Investors with more than one property can sometimes use combined equity across the portfolio as collateral for a single new loan, rather than refinancing any individual property's first mortgage. This can unlock capital without disturbing the rate on a property you'd rather leave alone, though it does tie multiple properties together under one loan.
Portfolio line of credit: Similar in spirit to a blanket loan but structured as a revolving line secured against a pool of properties, this option suits investors who repeatedly draw capital, repay it, and draw again as they cycle through acquisitions, a pattern common among BRRRR investors.
Tapping a different property in the portfolio: If the renovated property doesn't have enough seasoned equity yet, or its existing rate is worth protecting, investors sometimes pull cash from a different property in the portfolio that has more room, rather than refinancing the one that was just renovated.
1031 exchange: When the goal is redeploying capital rather than pocketing cash, a 1031 exchange lets an investor sell a property and roll the proceeds into a new one while deferring capital gains tax. It doesn't put cash in hand the way the other options do, but for investors focused on growing the portfolio rather than accessing liquidity, it's a path worth comparing.
Comparing the terms, draw structure, rate type, and effect on debt service coverage across these options against a straightforward cash-out refinance helps ensure the financing matches how and when you actually plan to use the capital.
Running the Numbers Before You Refinance
Every refinance decision should be backed by a clear calculation, not a general sense that rates or values have moved in your favor.
Total up the closing costs: Application fees, appraisal costs, title insurance, and recording fees typically add up to 2 to 5 percent of the loan amount, so start by pricing out the full cost of the transaction.
Find your break-even point: If the refinance is lowering your rate, divide total closing costs by the monthly savings to see how many months it takes to recoup the expense. If you plan to hold the property beyond that point, the math supports moving forward.
Compare cash-out returns to borrowing costs: If you are extracting equity, weigh the return you expect from deploying that capital against the cost of borrowing it. Extracted equity that earns less than it costs to borrow works against you.
Account for tax and opportunity costs: Consult a tax professional on how the refinance affects your deductions, and weigh whether the capital and effort might be better spent elsewhere before committing.
Running through this checklist before applying keeps a renovation refinance grounded in numbers rather than assumptions about market timing.
Refinancing after renovation represents a pivotal moment in your investment cycle. When executed with the right strategy, it unlocks the post rehab value you've created, rewards you for rent increases you've achieved, and provides capital for equity extraction that fuels your next deal. The best strategies for refinancing after renovation balance timing, documentation, loan selection, and portfolio goals to ensure every refinance moves you closer to your financial objectives.
Success comes from treating the refinance as a strategic decision, not just a financial transaction. By waiting for income stabilization, documenting your improvements thoroughly, choosing loan products that match your investment plan, and avoiding common mistakes, you position yourself to maximize returns and scale efficiently. Whether you're using DSCR loans for streamlined qualification or executing cash-out refinances to grow your portfolio, the principles remain the same: refinance with purpose, model your numbers carefully, and always keep your long-term strategy in focus.
As you move forward with your next renovation project, build your refinance strategy into your initial underwriting. Know when you plan to refinance, what loan product you'll target, and how the extracted equity will support your growth. This level of planning separates investors who sporadically capture value from those who systematically build wealth through real estate.